

MoBill Budget and Reminder

- 1.56K Reviews
- 4.0
- Downloads
- 500,000+
Our take on MoBill Budget and Reminder from Appgk
Managing household money is rarely difficult because of one large bill. The trouble usually comes from small payments, different due dates, forgotten subscriptions, and the vague feeling that everyone is keeping their own version of the budget. I tested MoBill Budget and Reminder with that kind of everyday situation in mind, and I found it most useful as a straightforward place to record personal finances and remember upcoming obligations. It is a free finance app from MoBill Apps, aimed at keeping budgeting practical rather than turning it into a complicated accounting project.
The app has been around since February 2011, and that long presence gives it a more established feel than a newly released budgeting tool. It currently sits at version 5.3.1, supports Android 8.0 and later, and has passed half a million installs. Its average score is 4.0 from roughly 3.8 thousand ratings, with about 1.6 thousand written reviews. Those figures suggest a useful but not universally loved tool: people clearly find value in it, while some users will want a more modern or more automated experience.
How it fits into a shared household
My first useful test for this app was not a personal spending plan but a shared household routine. Imagine two adults handling rent, utilities, groceries, transport, and occasional school or medical costs. One person may remember the electricity bill while the other notices that the grocery budget is disappearing early. A reminder-based budget app can help make those responsibilities visible, but only if both people agree on what gets recorded and who is responsible for updating it.
MoBill Budget and Reminder works best when treated as a shared notebook with structure. I would use it to enter recurring obligations, note expected spending, and check the plan before making a purchase. It is less suitable as a live household dashboard where every person automatically sees the same information from separate devices. That distinction matters. A couple or family can coordinate around the app, but they should not assume that installing it creates shared access or synchronized accounts.
Best Parts of MoBill Budget and Reminder
Things to Keep in Mind About MoBill Budget and Reminder
For a household using one tablet or one phone, the approach is simple: keep the device in an agreed place, open the app during a weekly money check-in, and review what has been entered. This is particularly practical for households where one person handles most administration but wants the other person to see the plan. The app becomes a prompt for conversation instead of a silent record that only one person understands.
A realistic example would be a family paid at the end of the month. On payday, I would record the fixed commitments first, then set aside room for food, travel, and irregular costs. Before a weekend purchase, I could check whether the relevant category still has room. When a bill is approaching, the reminder side of the app gives the household a reason to review the balance rather than relying on memory. The value is not that it makes decisions for you; the value is that it puts the decision in front of you at the right time.
News and Features Related to MoBill Budget and Reminder

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Why a shared device can be useful
A shared-device setup avoids one common problem with personal finance apps: information becoming trapped on one person’s phone. If the household already has a designated tablet or an older Android phone, MoBill can serve as a visible household ledger. That arrangement is especially helpful for partners who prefer to discuss spending face to face rather than exchange constant notifications.
There is a trade-off, though. A shared device requires discipline. Whoever enters a purchase needs to do it consistently, and the household needs a clear rule about whether an expense is recorded when it is planned, paid, or charged to a card. Without that agreement, the figures can look precise while still being misleading. I would establish that rule before relying on the app for important decisions.
Don't want to read the full review?
The same limitation applies when several people contribute to the budget. A teenager might tell a parent about a school expense, or one partner might pay for a repair and expect the other to add it later. MoBill can support the record-keeping habit, but the coordination still happens between people. That is not a flaw unique to this app, but it is important when comparing it with services built around automatic account sharing.
Setting boundaries before entering household finances
Good budgeting starts with deciding what belongs in the app. I would not begin by entering every historical transaction. That creates work before the household has agreed on its categories. A better approach is to start with the next payment cycle: fixed bills, planned essentials, and a small group of flexible spending areas. Once the routine feels manageable, older information can be added if it will genuinely help.
Screenshots
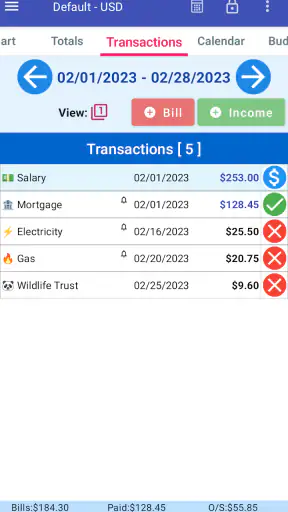
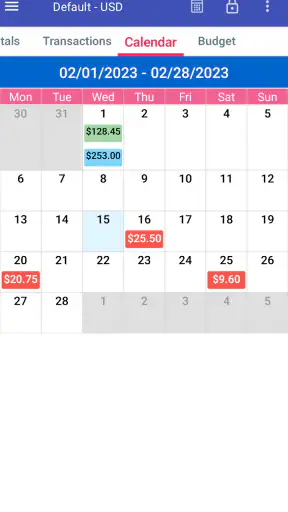
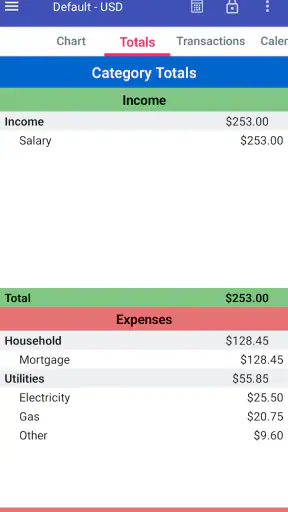
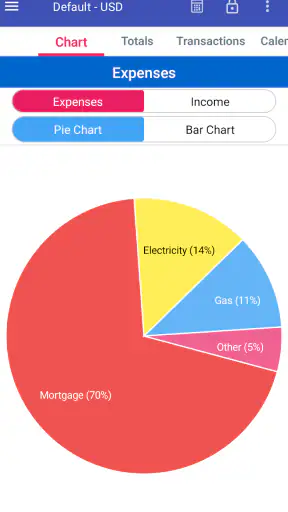
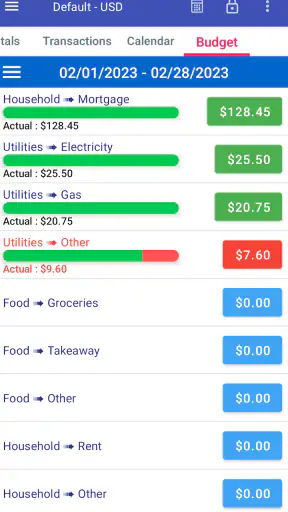
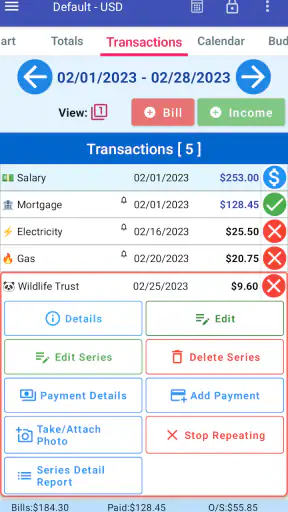
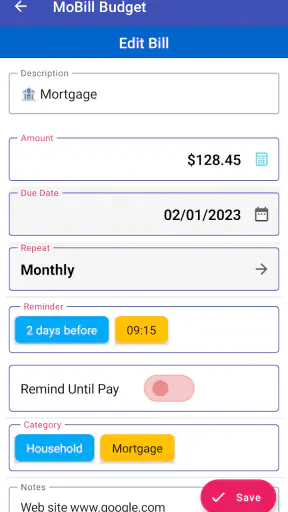
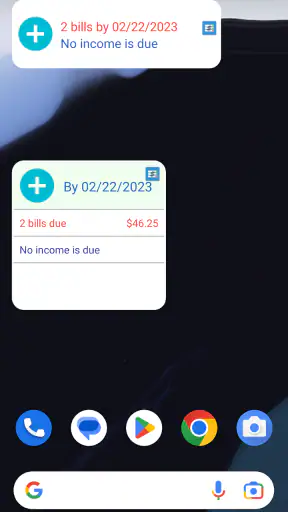
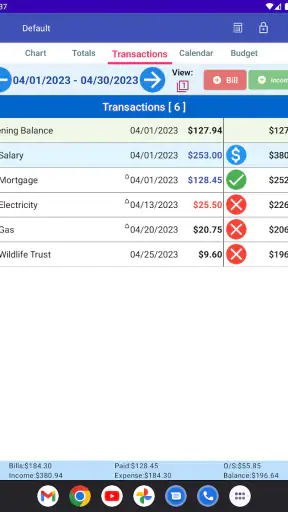
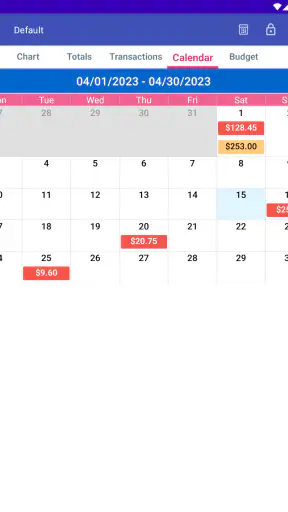
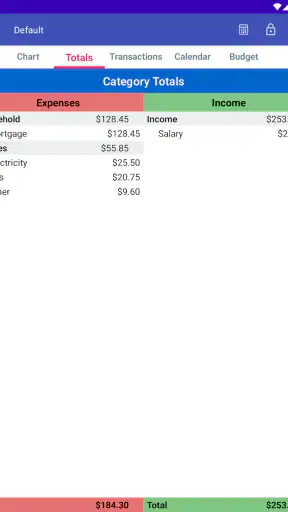
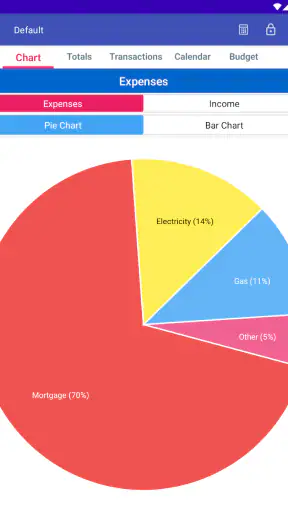
For shared use, I recommend separating personal and household money at the planning stage. Household rent, utilities, and groceries should not be mixed casually with one person’s hobbies or private purchases. If the app is being used on a common device, everyone should agree on whether personal spending will be included at all. Some families may want one overall picture; others will find that recording private purchases creates unnecessary tension.
The most important boundary is not technical; it is social. Decide who may view the entries, who is expected to add transactions, and what the figures will be used for. A budget should help people make choices, not become a tool for monitoring every small purchase. This is particularly important when multiple adults share finances but keep some spending separate.
I would also keep the reminder schedule realistic. Too many prompts can turn a helpful routine into background noise. The useful reminders are the ones tied to action: review an upcoming bill, check a category before a planned purchase, or update the budget after payday. If every minor expense generates an interruption, people are more likely to ignore the whole system.
What to prepare before relying on reminders
Before entering a bill, I would gather the information needed to recognize it later: the name of the expense, its usual amount or range, the expected timing, and the person responsible for checking it. This small preparation step makes reminders more valuable because the alert has a clear purpose. A vague entry such as “monthly costs” is less useful than a specific household obligation.
Irregular expenses deserve special attention. Annual renewals, seasonal clothing, school materials, vehicle maintenance, and gifts can make a monthly budget look healthier than it really is. I would create a separate planning habit for these costs rather than pretending they are ordinary weekly spending. The app can help keep them visible, but the household still needs to estimate and reserve for them.
Another practical boundary is deciding how to handle shared cards or cash. If two people use the same payment method, the person who notices the transaction should record it, even if someone else made the purchase. If cash is involved, update the app at a set time instead of waiting until the details are forgotten. The system works only when the record is close enough to reality to guide the next decision.
Coordinating money without assuming automatic sharing
MoBill Budget and Reminder is appealing for people who want direct control over entries rather than a finance service that pulls information from banks. That can feel calmer for a household that prefers manual review, and it avoids making the budget dependent on whether every account connection continues to work. On the other hand, manual entry demands consistency, especially when several people are spending from the same plan.
I would use a short weekly meeting as the coordination layer. One person opens the app, the other checks recent purchases, and together they look at the next few obligations. This does not need to become a formal financial meeting. Ten minutes can be enough if the categories are already clear. The important part is to resolve discrepancies while they are small, rather than discovering at the end of the month that one person has been using a different definition of “available.”
For couples with separate phones, I would treat the app as one person’s budgeting workspace unless both people have independently confirmed how they will exchange updates. Do not build a household plan around an assumed multi-user feature. If everyone needs simultaneous access, automatic synchronization, or account-level permissions, a dedicated shared-finance service may be a better fit. MoBill’s strength is its direct, personal budgeting approach, not an elaborate collaboration system.
A useful workaround is a simple division of responsibility. One person maintains recurring commitments, while the other checks flexible categories and reports unusual expenses. This prevents the app from becoming a second job for one household member. It also makes errors easier to spot: if the bill section is current but grocery spending is not, the household knows exactly which part of the routine needs attention.
Using the app alongside ordinary alternatives
The usual alternative is a spreadsheet. A spreadsheet offers more freedom, especially for households that want custom formulas, shared editing, or detailed year-to-year analysis. It can also become fragile when someone changes a formula or forgets which sheet contains the current version. MoBill is more focused: it encourages a budgeting and reminder routine without asking the user to design the entire system.
A paper notebook is faster for some people and works well during a conversation, but it is easy to misplace and less convenient when a reminder must happen later. MoBill has the advantage of keeping the budget on a device that is already part of daily life. The compromise is that users who dislike typing transactions on a phone may find paper more natural.
Banking apps are another common choice. They are convenient for checking balances and recent transactions, but they may not provide the planning style a household wants. MoBill makes more sense when the goal is to decide where money should go, not simply to look backward at what has already left an account. If automatic transaction importing is essential, I would choose a different category of tool.
For a family that wants sophisticated reports, investment tracking, multiple synchronized profiles, or detailed permission settings, I would also look elsewhere. MoBill can be a good lightweight organizer, but it should not be mistaken for a full financial management platform. Its appeal is strongest when the household values simplicity and is willing to maintain the information manually.
Age, trust, and who should use it
The app carries an Everyone content rating, which makes its general presentation appropriate for a broad audience. That does not mean every child should manage household finances alone. Money decisions involve judgment, privacy, and consequences that are separate from an app’s age label. I would introduce it to a younger user as a learning tool under adult guidance, not as an independent account manager.
For teenagers, a limited personal budget can be a useful exercise. A parent could agree on a few categories, review the plan together, and use upcoming reminders to discuss priorities. The important point is transparency: the young person should know what is being recorded and why. The app should support trust and learning, not operate as a hidden surveillance method.
For adults sharing a device, trust works in the other direction. Everyone should understand that entries may be visible to anyone who can open the budgeting workspace. I would avoid entering sensitive details that do not serve the household plan, particularly if the device is accessible to guests or children. A shared budget does not require a complete record of every private financial matter.
Older relatives may appreciate the clear purpose of a reminder-based finance app if they are comfortable using Android. The minimum operating system is Android 8.0, so compatibility should be checked on an older device before making it the household’s main budgeting tool. If the app cannot be used on the intended phone or tablet, the best budgeting method is the one the household can actually access and maintain.
The free price makes trying it low-risk, although in-app purchases range from $2.50 to $10.99 per item. I would look at the available paid options inside the app and decide whether they solve a real problem for the household before purchasing anything. A shared-device user should be especially careful about who can approve purchases, since the person maintaining the budget may not be the person who owns the device or payment method.
Everyday friction and practical limitations
The biggest limitation I noticed in this style of budgeting is the need for accurate input. MoBill cannot know that a cash purchase happened unless someone records it, and a reminder cannot correct an unrealistic budget. This is manageable for a person who enjoys keeping organized notes, but frustrating for someone who expects the app to do most of the work automatically.
There is also a psychological risk in treating the planned amount as permission to spend. A category can show room while a large annual expense is approaching. I would use the app as a decision aid, then consider the household’s wider commitments before spending. The numbers are useful only when the categories reflect real priorities and irregular obligations.
Another point is household disagreement. Two people may agree that groceries matter but disagree about whether takeaway meals belong there, or one may treat a child’s activity as a household cost while the other treats it as discretionary. The app cannot settle those definitions. I would write down the household’s category rules in plain language and review them when the budget repeatedly feels wrong.
Finally, simplicity can feel restrictive to advanced users. Someone who wants to model debt repayment scenarios, compare several income streams, or build complex forecasts may quickly outgrow a lightweight mobile budget. In that case, a spreadsheet or more specialized finance application is a better companion. I would rather use MoBill for the daily routine and a separate tool for deeper planning than force it to do a job it was not designed for.
My household verdict
After using it as a practical budgeting and reminder tool, I see MoBill Budget and Reminder as a sensible choice for people who want a clear, manual way to organize everyday finances. It works particularly well for a household that shares one device, holds short weekly money check-ins, and agrees on who records what. The free entry point also makes it easy to test the routine before committing to it.
I would recommend it to a couple managing ordinary bills, a single user who wants reminders for recurring obligations, or a parent introducing a teenager to basic budgeting with supervision. I would not recommend building a complex multi-person financial system around it without first confirming that its workflow matches the household’s access and coordination needs.
The app’s 4.0 average and substantial install base fit my impression: it is established and useful, but not a perfect answer for every budgeting style. MoBill Apps has kept the focus on personal finance and budget control, and that focus is its main advantage. It does not need to replace a bank app, spreadsheet, or conversation between household members to be worthwhile.
My final advice is to start small. Enter the next set of household obligations, agree on category boundaries, schedule only reminders that lead to action, and review the plan together once a week. If that routine reduces forgotten bills and makes spending conversations easier, the app is doing its job. If you need automatic imports, detailed collaboration, or advanced financial analysis, choose a more specialized alternative instead. For a modest, shared-device budgeting habit, however, MoBill Budget and Reminder remains a practical option worth trying.
MoBill Budget and Reminder FAQ
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by tracking bills, recurring payments, budgets, and reminders in one place. After setting up your expenses, you can monitor upcoming due dates and see how regular payments affect your available money. It is especially useful for users who want a simple overview of household bills without relying on spreadsheets.
Can I create recurring bills and payment reminders in MoBill?
Yes, recurring expenses and reminders are one of the app’s main purposes. You can generally enter information such as the bill name, amount, payment frequency, and due date, then receive a reminder before the payment is expected. This can be helpful for rent, subscriptions, utilities, insurance, and loan payments. However, reminder behavior may depend on your device’s notification permissions and system settings.
Does MoBill Budget and Reminder connect directly to my bank account?
MoBill is primarily a manual budgeting and bill-reminder tool rather than a full bank-account aggregation service. You should expect to enter or update financial information yourself unless the version available on your device specifically offers an integration. This approach can provide more privacy and control, but it also means that balances and transactions may not update automatically when payments are made.
Is MoBill Budget and Reminder free to download and use?
The availability of free features, advertisements, and optional paid upgrades can vary according to the platform and the current version of MoBill. Before downloading, check the Google Play Store or Apple App Store listing for pricing details, in-app purchases, and subscription information. The free version may be enough for basic reminders, while advanced budgeting or customization features could require payment.
Is my financial information safe when using MoBill?
Before entering sensitive financial details, review the app’s privacy policy and the permissions requested during installation. A budgeting app may only need local information such as bill names, amounts, and dates, but data handling practices can differ between versions. Avoid storing passwords, banking login credentials, or unnecessary personal information, and keep your device protected with a secure lock and updated operating system.











